Inflation, Interest Rates and Gold: A Beginner’s Guide
Understand how inflation and interest rates influence gold, why real returns matter, and how owning gold differs from participating in gold operations.
Key takeaways
- Inflation reduces purchasing power, so a growing savings balance can still lose value in real terms.
- Real interest rates account for inflation and help explain the appeal of interest-paying assets relative to gold.
- Gold responds to expectations, currencies and demand as well as inflation; no single indicator determines its price.
- TGC represents participation in our unified operating pool, not direct tracking of the gold price, and its value can fall.
Your groceries cost more. Your savings account pays more interest. Yet gold is moving in a direction you did not expect. Which signal should you trust?
At Teqwah, we believe understanding gold starts with understanding the forces around it. Inflation, interest rates and gold are connected, but not by a simple rule that says one rises whenever another falls.
Let’s follow those connections through everyday decisions—and explore why the price of gold and the performance of a gold business are different stories.
Gold responds not just to rising prices, but to what money can earn after inflation—and what investors expect next.
1. When everyday costs rise, what happens to your savings?
Imagine a shopkeeper who spends more each month replacing the same stock. Transport costs have increased. Suppliers charge more. Eventually, the shopkeeper raises prices too.
Inflation is a broad increase in prices over time. It reduces purchasing power: the amount your money can buy. One expensive item does not establish inflation, but rising costs across many goods and services can.
For a young saver, the important question is not just, “Has my balance grown?” It is, “Can that balance buy more than before?”
Suppose savings earn 3% over a year while prices rise 5%. These are hypothetical figures, not current rates. The balance grows, but its purchasing power falls. The approximate return after inflation is minus 2%, before taxes or fees.
This is why people look for assets that might preserve purchasing power. Gold is one candidate, but it is not a dependable short-term match for the cost of living.
Why this matters: A bigger account balance does not automatically mean greater spending power.
2. Why do interest rates change the picture?
Interest is the price of borrowing money and a potential reward for lending or saving it.
Central banks often raise policy rates to help cool inflation. Higher borrowing costs can discourage spending and investment, easing pressure on prices. Lower rates can support borrowing and demand. These effects take time, and rates cannot directly solve every supply shortage.
For a household, higher rates might mean a more expensive loan but a better deposit rate. For someone considering gold, they also change the alternatives.
Physical gold pays no interest. If a savings account or bond offers a more attractive return, holding gold can become less appealing by comparison. Economists call this opportunity cost: what you give up by choosing one option over another.
But the advertised rate is only half the story.
The real interest rate is the interest rate adjusted for inflation. A useful approximation is:
Real interest rate ≈ nominal interest rate − inflation.
“Nominal” simply means the stated rate. Investors also watch expected inflation, because future purchasing power matters when choosing where to hold money today.
3. Does higher inflation always push gold higher?
No—and this is where many beginners get caught out.
Gold can attract demand when people worry about weakening purchasing power, financial stress or uncertainty. Yet higher inflation can also lead investors to expect higher interest rates. If real yields rise, interest-paying alternatives may become more competitive with gold.
Picture two possible situations:
- Inflation rises faster than interest rates: Cash returns may lose more purchasing power, potentially supporting gold demand.
- Interest rates rise faster than inflation: Real yields may improve, potentially creating a headwind for gold.
Neither is a prediction. Currency movements, central-bank purchases, jewellery demand and investor sentiment also matter.
Gold is commonly quoted internationally in US dollars. A stronger dollar can make it more expensive for buyers using other currencies, potentially weighing on demand. Your own currency’s movement can also change your local gold return.
Markets look ahead, too. Gold may react to an expected rate cut before the cut happens. That helps explain why a headline and a price move can appear to contradict each other.
Why this matters: Ask what changed relative to expectations—not simply whether inflation is high.
4. Buying gold is not the same as backing gold operations
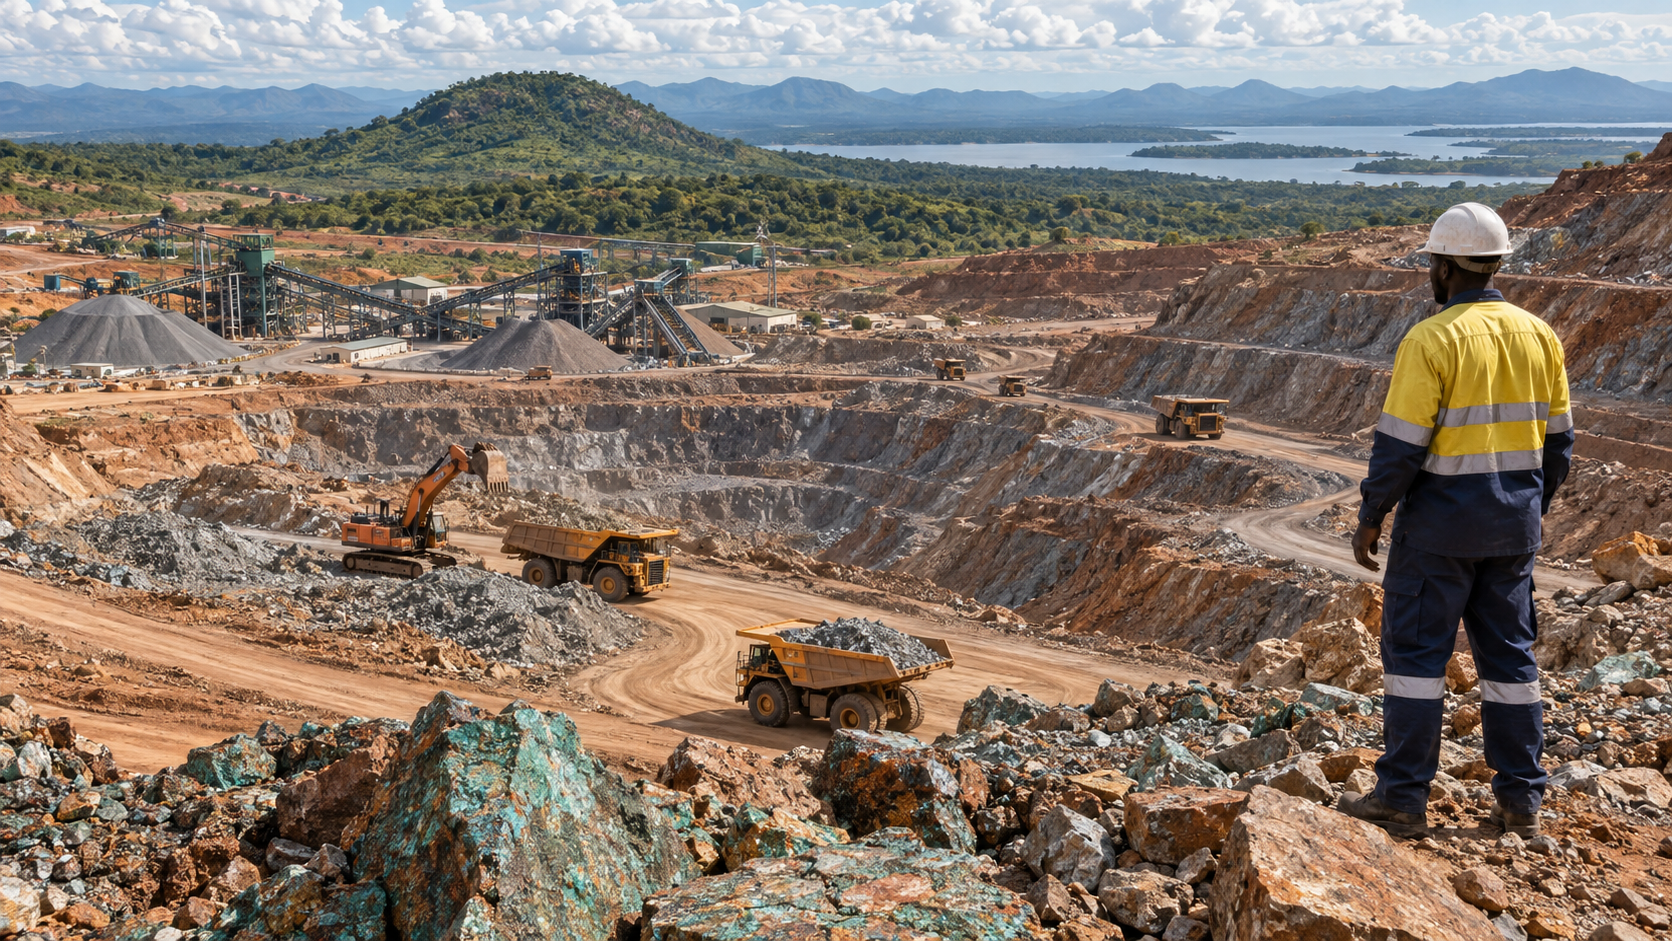
Now imagine a small miner. A higher gold price could increase revenue from each unit sold. But fuel, wages, equipment maintenance and processing costs may also rise.
More valuable output does not necessarily mean more profit. Production volumes, recovery rates—the share of gold successfully extracted—and downtime all affect the result.
That distinction is central to our approach at Teqwah. Our operations span gold mining, physical gold trade, productive machinery and selected real estate. Participants hold TGC, a divisible participation unit representing a proportional share of our unified pool; they do not choose individual projects.
TGC is not an exchange-traded gold product or a direct quotation of the gold price. Its recorded value is our recorded pool value divided by circulating TGC. Recorded operating results affect that value, which can rise or fall.
For people who see potential in gold but cannot run a mine themselves, our model offers participation in operations we select and manage. The opportunity is exciting precisely because value must be created through execution—not assumed from a gold-price headline.
5. What should you check before making a decision?
Start with the job you want your money to do. Emergency savings, long-term purchasing power and participation in a business are different needs.
Before choosing an investment, ask:
- What am I holding? Physical metal, a traded product or participation in operating assets?
- Where could returns come from? Price changes, interest or business results?
- When can I access my money? Check selling conditions, lock-ups and payout arrangements.
- What could reduce my outcome? Consider fees, inflation, currency movements and operational losses.
At Teqwah Capital, we encourage readers to understand the mechanics before participating. Asset backing does not remove risk, and a connection to gold does not create an automatic inflation hedge.
Frequently asked questions
Is gold a reliable inflation hedge?
Gold may help preserve purchasing power over some periods, but its price can fall even when inflation is high. It does not track everyday prices consistently, especially over short periods.
Do falling interest rates always make gold rise?
No. Falling rates can reduce gold’s opportunity cost, but inflation expectations, currency movements and market positioning also influence prices. An expected cut may already be reflected in the price.
Does TGC move directly with the gold price?
No. Our TGC value follows recorded pool value divided by circulating units, not an exchange-traded gold quotation. Operating performance matters, and results can be positive or negative.
Ready to connect the headlines with how participation works? Explore Teqwah and TGC →
Investing involves risk and values can fall. This article is educational and is not financial advice.
Teqwah view
At Teqwah, we connect participation with gold mining, physical gold trade and productive operations through one divisible unit, TGC. We see opportunity in putting capital to work, while keeping the distinction clear: our recorded value depends on the pool and operating results, not simply a rising gold price.
Sources
Investing involves risk. TGC value can fall. This is not investment advice.
Comments
No comments yet — be the first.