Yoco’s route to 200,000 businesses began with a bank willing to bet
The South African payments company grew from a card reader into a technology platform after overcoming a funding setback and a lockdown collapse in transactions.
Key takeaways
- Yoco has grown from a card-reader business into a technology platform serving 200,000 small businesses.
- Mercantile Bank provided access to the payments system, while angel investors filled a gap left by an institutional investor’s withdrawal.
- The cheaper Yoco Go device helped attract 15,000 merchants in a single month in 2019, according to co-founder Lungisa Matshoba.
- Transaction volumes fell about 90% at the height of lockdown; Yoco subsequently published data tracking the recovery.
- All four founders remain involved, with former CEO Katlego Maphai serving as a strategic adviser after stepping down in 2025.
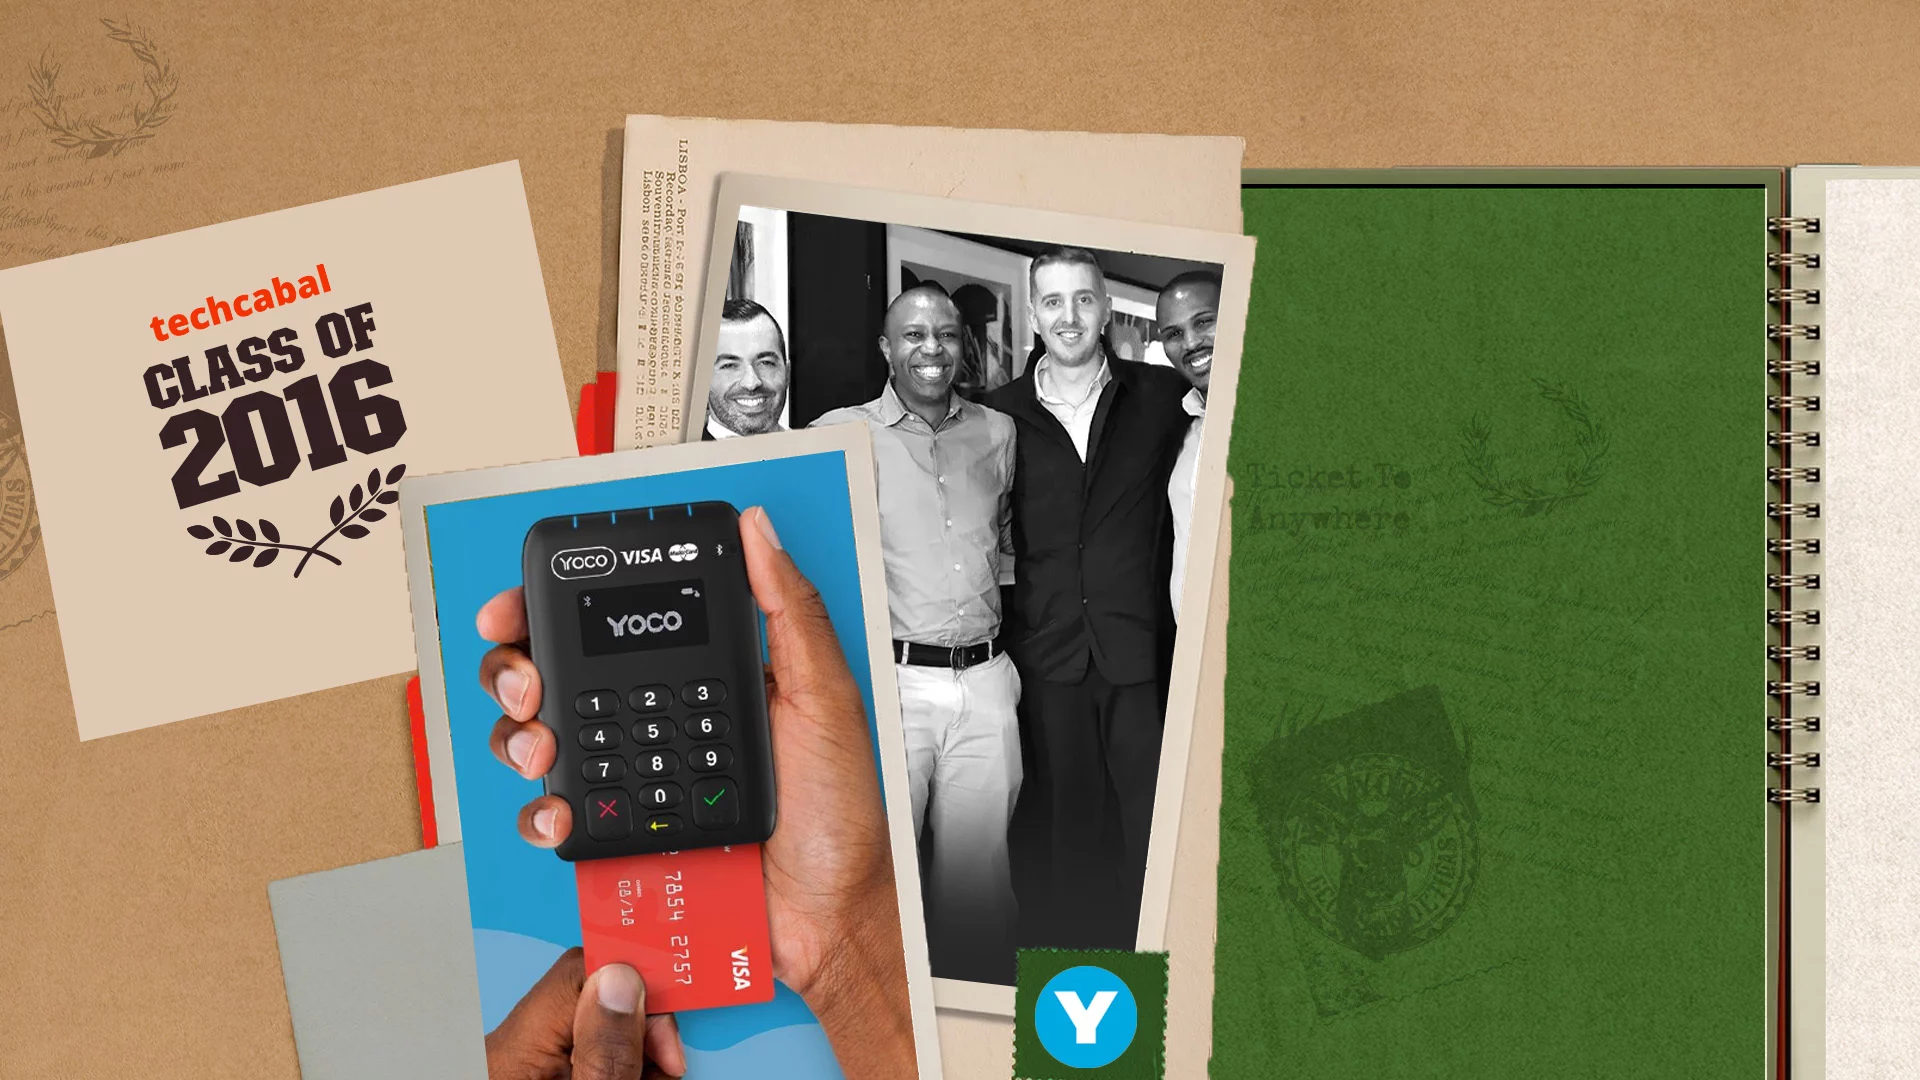
Yoco finally persuaded a bank to let it into South Africa’s payments system—then the institutional investor expected to fund its next step withdrew. Its angel investors, individuals backing the young business, filled the gap. According to TechCabal, that early scramble helped keep alive a company that now serves 200,000 small businesses, having started with a simple card machine.
Carl Wazen, Katlego Maphai, Lungisa Matshoba and Bradley Wattrus began working on Yoco around 2013. Their starting point was a mismatch: South Africans were using cards more often, but small merchants struggled to accept them. Between 2010 and 2014, card transactions rose from 1.02 billion to 1.96 billion. Cards in circulation increased from 58 million to 90 million. Yet bank applications, paperwork, equipment and fees kept card acceptance out of reach for many smaller businesses.
A bank first, then a funding rescue
A reader alone could not solve that problem. Yoco needed an acquiring bank, which connects merchants to card networks and processes their payments. Wazen, the company’s co-founder and chief business officer, told TechCabal that securing a banking partner consumed the founders’ first year. With no trading history or payments track record, they had to demonstrate how they would recruit legitimate merchants, control risk and support customers. Their aim was to work through banking infrastructure, not build a competing bank.
Funding brought another obstacle. Local venture capital investors—firms that finance young businesses—were sceptical, and Yoco’s initial $560,000 came largely from angels. Wazen drew on professional contacts in the Middle East; early supporters included Robby Hilkowitz and Greg Kidd. Mercantile Bank eventually approved the partnership. But after that approval, an institutional investor that had issued preliminary investment terms pulled out. Wazen did not give a reason. The angels increased their backing, providing enough money to build the product and bring merchants aboard without an institutional lead investor.
Wazen told TechCabal that, for an entire year, Yoco repeatedly had only about 90 days of cash left to operate.
Yoco formally launched in October 2015 following a year-long test involving more than 500 merchants. The founders handled sales, customer setup and support themselves. Wazen said the product required no formal training, while recommendations helped establish its first customer base in Cape Town. During 2016, merchant numbers rose from roughly 500 to 5,000. Digital marketing, inbound sales and self-service registration made growth more repeatable: Yoco added 400 merchants in July and was adding more than 800 a month by November.
Cheaper hardware, then a sudden stop
The 2019 launch of Yoco Go, a smaller and cheaper card machine, opened another growth channel. Matshoba said the company registered 15,000 merchants in one month. Then COVID-19 exposed how closely Yoco’s fortunes followed those of its customers. As South African businesses reduced or halted operations during lockdown, transaction volumes on its platform fell by about 90% at the worst point.
Yoco turned some of that disruption into information. It published transaction figures and built a live dashboard showing recovery across provinces and industries. All four founders remain involved: Matshoba leads product and technology, Wattrus is chief financial officer, and Wazen runs the business side. Maphai stepped down as chief executive in 2025 but remains a strategic adviser.
The next issue to watch is how Yoco adapts its broader platform to the needs of its 200,000 small-business customers. Its history offers a clear measure for that task: making payments easier for merchants while remaining resilient when their trade slows.
Sources
Investing involves risk. TGC value can fall. This is not investment advice.
Comments
No comments yet — be the first.