Uganda’s Shs5 trillion tax breaks face a value-for-money test
A new study puts the cost of tax relief at 15.5% of tax collections, while warning that removing VAT exemptions could push more households into poverty.
Key takeaways
- Uganda’s tax expenditure was estimated at Shs5.01 trillion in FY2024/25, equivalent to 2.2% of GDP.
- Strategic investor tax-holiday beneficiaries increased from two firms in 2018 to 123 in 2025, but their local sourcing share declined.
- Removing current VAT exemptions could raise national poverty by 5.46 percentage points, according to the study.
- Missing returns and incomplete data make it difficult to judge whether incentives achieve their intended results.
- The policy challenge is to distinguish productive investment incentives and effective social relief from tax breaks that do not justify their cost.
Uganda gave up an estimated Shs5.01 trillion in tax revenue in FY2024/25, yet scrapping exemptions is no simple fix. A new study estimates that removing current value-added tax exemptions would lift national poverty from 16.08% to 21.54%. Those findings capture the challenge facing policymakers: recover revenue without undermining investment or making vulnerable households poorer.
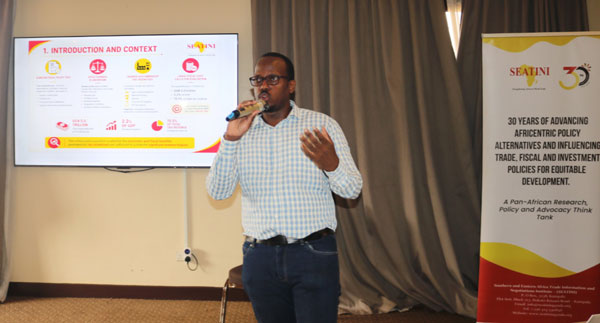
According to The Independent Uganda (direct), the cost-benefit analysis was discussed in Kampala on September 25, 2026, at a meeting convened by SEATINI-Uganda, a regional trade policy institute, with the Uganda Revenue Authority. The dialogue received support from the Embassy of Ireland through the STRIDe tax and revenue improvement project. The central issue was whether tax relief delivers enough economic and social benefit to justify its cost.
A large bill, with different beneficiaries
The study put tax expenditure—revenue forgone through exemptions, reduced rates and other relief—at about 2.2% of gross domestic product and 15.5% of total tax collections. Finance ministry tax specialist Solomon Rukundo said VAT, a tax on consumption, accounted for about Shs2 trillion. Personal income tax relief was roughly Shs1 trillion, followed by excise duty at Shs853 billion, customs duty at Shs708 billion and corporate income tax at Shs431 billion.
The beneficiaries extend well beyond private investors. Security personnel, retirement fund contributions and members of parliament featured among the main categories receiving personal income tax relief. Mining, oil and gas, and government projects accounted for a substantial share of VAT relief. Each exemption reduces Treasury receipts, but its purpose may range from attracting a factory to supporting households. SEATINI’s Jane Nalunga framed the issue as one of public accountability:
“We are not tax experts. But we are taxpayers. This is our money,” Nalunga said.
The stakes are rising as Uganda pursues its Tenfold Growth Strategy, which aims to expand the economy from roughly US$50 billion to US$500 billion by 2040. Agro-industrialisation, tourism, minerals including oil and gas, and science, technology and innovation are its main anchors. The government also wants a larger formal economy and a broader domestic revenue base, making the cost of incentives harder to ignore.
More investment, but weaker local sourcing
The number of firms receiving the strategic investor tax holiday rose from two in 2018 to 123 in 2025. Beneficiaries reported higher investment, turnover, profits, wages and purchases after receiving incentives. But imports increased faster than local purchases, and the share of goods sourced locally fell. That raises a separate test for the growth strategy: whether attracting investors also builds stronger Ugandan supply chains.
Measuring that return remains difficult. The study identified gaps in reporting, monitoring, evaluation and data, despite progress through annual tax expenditure reports and other oversight tools. Some reliefs are not yet fully costed. Ronald Nyenje Makumbi of the Uganda Revenue Authority said some beneficiaries do not file returns, while others provide too little information to establish whether incentives delivered their intended benefits.
The social findings also argue against treating every exemption alike. The estimated poverty increase from removing VAT exemptions was larger among households with children and those headed by women. An exemption protecting household spending therefore has a different purpose from relief designed to encourage business investment, even though both reduce revenue.
The next test is whether Uganda can connect incentives to measurable results: jobs, exports, domestic value added and local suppliers. Policymakers also need to establish whether investment would have happened without the relief. The ministry has already recognised cost-benefit analysis as a tool for reviewing incentives. Better beneficiary data will be central to deciding which breaks earn their place—and which do not.
Sources
Investing involves risk. TGC value can fall. This is not investment advice.
Comments
No comments yet — be the first.