Why Uganda’s pension fund passed on Kenya Pipeline as the state bought in
NSSF rejected Kenya Pipeline’s IPO price, while Uganda’s government pursued a stake to protect its fuel supply.
Key takeaways
- NSSF declined KPC’s IPO because it judged the 9 Kenyan shillings offer price too high for its return requirements.
- Old Mutual Investment Group Uganda estimated fair value at 4.61 Kenyan shillings per share, 49% below the IPO price.
- Uganda’s government prioritised fuel security, securing a major stake, board representation and veto rights.
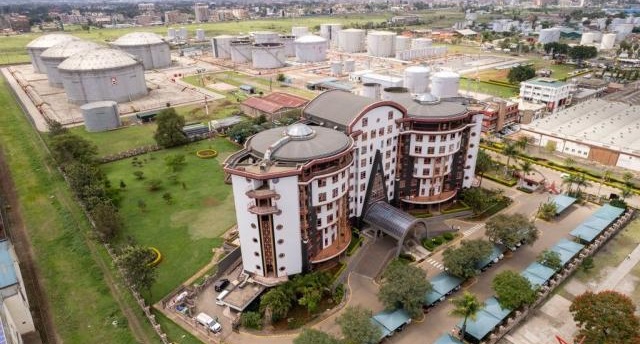
- KPC handles 95% of Uganda’s fuel supplies, giving the investment significance beyond financial returns.
- The report described limited trading activity and prices largely anchored near the IPO level.
Uganda’s government saw an opportunity to secure its fuel lifeline. Its national pension fund saw a price it could not justify. The National Social Security Fund stayed out of Kenya Pipeline Company’s initial public offering, or first sale of shares to public investors, because it considered the shares too expensive, according to The Independent Uganda, reporting Uganda Radio Network’s account. The split exposes two different priorities: earning returns for savers and gaining influence over essential energy infrastructure.
NSSF Deputy Managing Director Gerald Kasaato said the offer price of 9 Kenyan shillings per share did not offer the returns the fund sought under prevailing conditions. He pointed to a price-to-earnings ratio of about 21, meaning investors were paying roughly 21 shillings for each shilling of annual profit. Kasaato contrasted KPC with Safaricom, whose growth prospects had helped justify NSSF’s participation in that company’s offering.
A growing investor draws a line
The decision was not a retreat from shares. NSSF has acquired significant stakes in MTN Uganda, Airtel Uganda and Kampala Marriott Hotel, while increasing its holdings in Safaricom, KCB and other regional stocks. Equities now account for 18.4% of its portfolio, with those holdings worth about 5.93 trillion Ugandan shillings, the report said. Chief Investments Officer Kenneth Owera said the fund conducts extensive analysis before committing money. Its refusal to buy KPC also came amid pressure from Ugandan officials to invest in infrastructure and development projects.
Old Mutual Investment Group Uganda reached a similarly cautious conclusion on price. Using estimates of future cash flows and comparisons with other investments, it calculated a fair value of 4.61 Kenyan shillings per share—49% below the IPO price. Its company valuation was 77.4 billion Kenyan shillings, compared with the offering’s valuation of 163.56 billion. Those figures represented the firm’s assessment, rather than an established market value.
Old Mutual said it expected prices to adjust after listing as expectations settled and more active trading brought valuations closer to its estimate of underlying value.
The firm nevertheless viewed KPC’s profitability, dividends and distinctive regional position positively. Its concern was the entry price, not simply the business itself. The report said several analysts in Uganda and Kenya had also considered the offer expensive, highlighting the gap between a company’s strategic importance and the price investors were being asked to pay.
Fuel security changes the calculation
Uganda’s government used a different yardstick. As subscriptions lagged, Kenya agreed to Uganda’s demands for a 20.15% stake, at least two board representatives and veto rights over pipeline tariff changes, business plans, dividend policy revisions and changes to the company’s governing documents, according to the report. Uganda’s participation helped take the offer 5.7% above its target. The concessions gave the country influence beyond the prospect of investment income.
Energy Ministry Permanent Secretary Irene Bateebe defended the purchase as a strategic move to strengthen regional cooperation and safeguard national interests. KPC handles 95% of Uganda’s fuel supplies, while Uganda contributes roughly two-thirds of its transit traffic revenue. Bateebe argued that a major shareholding would make Uganda more than a passive customer. Ruth Nankabirwa, who oversaw the investment as the responsible minister, also pointed to the concessions as support for secure, accessible and affordable petroleum supplies.
The report described subdued trading during the six months after KPC’s March 2026 debut: shares stayed near 9 Kenyan shillings initially, briefly reached 10 around June, fell to 8.7 in August and returned to 9. It cited Uganda National Oil Company’s roughly 20.1% holding and the Kenyan government’s 35% stake as support for the stock. What bears watching next is whether trading becomes more active and prices move closer to the valuation Old Mutual outlined—or remain near the offer price.
Sources
Investing involves risk. TGC value can fall. This is not investment advice.
Comments
No comments yet — be the first.